
Every complete purchase offer must include the identified property and parties, a definite price and payment plan, earnest money terms, clear contingencies with deadlines, required disclosures, and signed contract pages, plus lender pre-approval or proof of funds attached. Set a firm acceptance deadline before you submit, and confirm every attachment is included so the listing agent can evaluate the offer without asking for missing pieces.
TL;DR:
- A lender preapproval based on credit and income carries more weight than a prequalification; cash buyers should attach a bank or brokerage statement.
- Earnest money commonly ranges from 1% to 10% by local custom; state a dollar amount, name the escrow holder, and tie refunds to contingency deadlines.
- Give each contingency its own deadline, notice process, and outcome; record countersignature and delivery timestamps because they establish compliance and support deposit refunds.
- Set an acceptance deadline with an exact time and time zone, and obtain both parties’ signatures on any written extension before it expires.
- Attach all signed contract pages with required initials and lender preapproval or cash proof; add the signed lead paint acknowledgment for homes built before 1978.
Table of Contents
- Offer essentials: property, price, and cost allocations
- Price and financing: what your lender documents can and can't promise
- Earnest money: amounts, escrow handling, and refund triggers
- Contingencies checklist: what to specify for each type
- Disclosures and addenda that must accompany your offer
- Timelines and deadlines: acceptance, removals, and extensions
- Submission packet checklist: what to attach before you send the offer
- What happens after acceptance: escrow through closing
- Running the checklist with a private tracking tool
- A habit worth building before your next offer
- An optional way to keep your offers organized
- FAQ
- Sources
Offer essentials: property, price, and cost allocations
A complete offer starts with precision. The property description should use the full legal address and, where your market requires it, the parcel or lot number, not just the street address pulled from a listing site. Name every buyer and seller exactly as they appear on the title or as the seller intends to take title, since a mismatch here can stall closing weeks later.
Price and payment structure come next. State the purchase price in whole dollars, then spell out the payment plan: down payment amount, loan amount, and any seller credits toward closing costs or repairs. If you're asking for a credit, write the dollar amount or percentage directly into the offer rather than leaving it for later negotiation.
Possession terms deserve their own line. Will the seller hand over keys at closing, or do they need a short rent-back period to arrange their move? NAR's consumer guide on offer essentials lists possession and closing dates among the core terms a complete offer must state, alongside price, parties, and contingencies. Spell out the rent-back duration, daily rate if any, and who covers utilities and insurance during that window.
Finally, allocate closing costs and prorations. Property taxes, HOA dues, and any prepaid utilities typically get prorated to the closing date, and your offer should state which costs the seller covers versus what you'll pay.
- Use the full legal address and parcel number, not just the street address.
- Name buyers and sellers exactly as they'll appear on title.
- Write the purchase price, down payment, and any seller credit as specific dollar figures.
- Specify possession timing and any rent-back terms, including daily rate and duration.
- List which closing costs and prorations the seller covers versus the buyer.
Price and financing: what your lender documents can and can't promise
Your offer needs proof that you can actually pay for the home, not just a promise that you intend to. A pre-approval letter from your lender, based on a credit pull and income documentation, carries more weight with sellers than a prequalification letter, which is often just an estimate. If you're paying cash, attach a bank or brokerage statement showing available funds instead.
It's worth understanding what your lender's paperwork does and doesn't cover. The Loan Estimate and Closing Disclosure are lender documents that outline loan terms, projected payments, and closing costs, but they aren't substitutes for the terms written into your purchase offer. Your offer should independently state the loan type, your financing approval deadline, and whether the deal depends on a specific interest rate or rate lock. Don't assume the lender's disclosures will fill in gaps the contract leaves open.
Appraisal shortfalls are one of the more common deal killers, and your offer should address them directly. An appraisal reflects a lender's risk assessment of the property's value, and when it comes in below the purchase price, buyers generally have three options: cover the gap in cash, renegotiate the price, or walk away if an appraisal contingency protects them. Some buyers include appraisal-gap language upfront, committing to cover a shortfall up to a set dollar amount, which can make an offer more competitive in a tight market. For a closer look at how these clauses work, our guide to appraisal gap coverage walks through common structures and trade-offs.
Deposits commonly range from 1% to 10% of the purchase price, though the right figure depends on local custom and how competitive the market is, according to NAR's reporting on earnest money practices.
- Attach a full pre-approval letter, not just a prequalification estimate.
- State your financing deadline and loan type directly in the offer.
- Decide in advance whether you'll include appraisal-gap language and to what dollar limit.
- Keep a copy of your Loan Estimate on hand, but don't rely on it to define contract terms.
Earnest money: amounts, escrow handling, and refund triggers
Earnest money signals that you're serious, and the amount you offer can influence how a seller weighs your bid against competing offers. There's no fixed national rule for the right amount: some markets see buyers offer 1% of the purchase price, while competitive markets can push deposits toward 10%, according to NAR's guidance on earnest money. Your offer should state the exact dollar amount rather than a percentage, so there's no ambiguity.
The contract also needs to say who holds the deposit and where. Typically a title company, escrow agent, or real estate brokerage holds the funds in a neutral account until closing or a contract dispute resolves things. Name that party and reference the escrow instructions directly in your offer.
Refund terms matter as much as the amount itself. Earnest money is generally protected by your contingencies: if you cancel within an inspection, financing, or appraisal contingency window and follow the required notice steps, you typically get your deposit back. Once contingency deadlines pass, or if you waive a contingency, the deposit can become harder to recover and may be forfeited if you back out. Our breakdown of earnest money versus down payment covers how these funds eventually apply toward your purchase if the deal closes.
- State the earnest money amount as a dollar figure, not a percentage.
- Name the escrow holder (title company, brokerage, or attorney) in the offer.
- Tie earnest money protection directly to your contingency deadlines and notice requirements.
- Confirm in writing what happens to the deposit if a contingency isn't met.
Contingencies checklist: what to specify for each type
Contingencies are the conditions that let you walk away from a deal, and each one needs a deadline, a notice procedure, and a clear outcome if it isn't satisfied. According to NAR's consumer guide on contract contingencies, the most common contingencies cover financing, appraisal, inspection, home sale, title, and HOA review, and each should be clearly articulated with its own timeline.
- Inspection: define the scope (general home inspection, pest, radon, sewer scope), set a response deadline, and specify how repair requests and negotiations will proceed if issues surface.
- Appraisal: confirm the lender orders the appraisal, and spell out your options (renegotiate, cover the gap, or cancel) if the value comes in short. For a deeper look at how appraisal contingencies function, see this buyer's guide to appraisal contingencies.
- Financing: set an approval deadline, list what evidence satisfies the contingency (loan commitment letter), and state what happens if your lender denies the loan.
- Title: require a lien and title search, set a cure period for the seller to resolve issues, and confirm you'll receive owner's title insurance at closing.
- Home sale or home-close contingency: if your purchase depends on selling your current home, include a kick-out clause that lets the seller keep marketing the property and gives you a window to remove the contingency if a better offer arrives; also note any HOA document review period.
Pro Tip: Request the HOA's governing documents and financial statements as soon as your offer is accepted, since review periods are often short and can run concurrently with your inspection window.
Every contingency you waive weakens your negotiating position if something goes wrong later, so weigh each one against how competitive the local market is before you decide what to drop.
Disclosures and addenda that must accompany your offer
Sellers are generally required to disclose known material defects, past repairs, and hazards affecting the property, along with HOA details when one applies. Review these disclosures closely before finalizing your offer, since they often reveal issues worth addressing in your inspection contingency or price negotiation.

For homes built before 1978, federal rules add a specific requirement. The EPA's lead-based paint disclosure rule requires sellers of target housing to provide a Lead Warning Statement, disclose any known lead-based paint or hazards along with available records, and give buyers an opportunity to conduct a lead inspection before becoming bound under the contract. Certification records tied to this disclosure should be kept on file for three years.
Beyond disclosures, several addenda commonly travel with the offer itself:
- Financing addendum: spells out loan terms and the lender's role in the transaction.
- HOA addendum: addresses association fees, rules, and document review timelines.
- Appraisal-gap or escalation addendum: states how a shortfall or competing bid will be handled.
- Inspection repair addendum: documents agreed-upon repairs or credits following the inspection period.
- Lead-based paint disclosure and acknowledgment: required for pre-1978 target housing, with buyer signature confirming receipt.
Each addendum should be labeled clearly and referenced by name in the main contract, so nothing gets lost in a stack of attachments.
Timelines and deadlines: acceptance, removals, and extensions
Vague deadlines create disputes, so every date in your offer needs a specific time, not just a day.
- Set an exact acceptance deadline, including the time and time zone, so there's no confusion about when your offer expires if the seller hasn't responded.
- Record contingency removal dates as calendar dates tied to the contract's execution date, and note the exact moment you receive the seller's countersigned acceptance, since that start date determines every downstream deadline.
- Use a count-receipt practice: save the email or portal timestamp confirming when a notice, repair request, or contingency removal was delivered, since disputes often hinge on who sent what and when.
- Request extensions in writing, specifying the new deadline and which contingency it affects, and get signatures from both buyer and seller before the original deadline passes.
Our guide on tracking contingency deadlines outlines a simple reminder system for agents and buyers juggling multiple properties at once, which becomes especially useful once several deadlines overlap in a single week.
Submission packet checklist: what to attach before you send the offer
A clean packet makes the difference between an offer that gets a fast response and one that sits in a listing agent's inbox while they chase down missing pieces.
Mandatory attachments include every signed contract page with initials where required, your lender's pre-approval letter or proof of funds for cash purchases, and any earnest-money receipt or wire confirmation once funds move.
Helpful but not always required attachments include a one-page summary of your contingency timeline, any appraisal-gap language spelled out separately for clarity, and HOA documents if you've already reviewed them.
- Combine every document into a single PDF rather than sending separate files.
- Label each addendum clearly by name (financing, HOA, inspection repair, and so on).
- Include direct contact information for your lender and title company so the listing agent can verify details quickly.
- Double check that every page requiring a signature or initial has one before sending.
Pro Tip: Name your combined PDF with the property address and submission date, which helps everyone involved find the right version when revisions come back.
What happens after acceptance: escrow through closing
Once the seller accepts, escrow opens and your earnest money moves into a neutral account, where it will later apply toward your down payment or closing costs if the sale closes. From there, the practical work begins.
- Schedule your home inspection promptly, since repair negotiations depend on getting results back within your contingency window.
- Order the appraisal and title search early, as both can take longer than expected and feed directly into your financing and title contingencies.
- Deliver any requested documents to your lender and title company without delay to keep the loan underwriting process on schedule.
- Complete the final walkthrough shortly before closing to confirm the property's condition matches what you agreed to.
- Track contingency removals as they happen and confirm funds-to-close figures with your lender a few days before signing.
For a fuller walkthrough of this stretch, see our buyer closing checklist.
Running the checklist with a private tracking tool
Keeping every checklist item, document, and deadline straight across several properties gets difficult fast, which is why some buyers and agents use a dedicated tracking tool instead of scattered notes. With a dedicated tracking tool, you can map each offer term, price, contingency deadline, attached document to a structured field tied to the specific property, so nothing depends on memory.
- Log count-receipt dates the moment you get a seller's countersignature or a contingency removal notice.
- Keep private notes on negotiation points and repair requests, which can matter later if an earnest-money dispute arises.
- Compare multiple active offers side by side when a buyer is weighing trade-offs between competing properties.
Our guide on post-tour actions for remote buyers covers a similar workflow for capturing details before an offer even goes out.
A habit worth building before your next offer
The single habit that saves buyers from costly mistakes is simple: record, attach, and confirm, every time. The moment you receive a countersigned acceptance or a contingency removal notice, save it and log the date immediately rather than trusting your memory or a scattered email thread. Disputes over earnest money and missed deadlines almost always trace back to a missing timestamp, not a missing clause.
— Antony
An optional way to keep your offers organized
Running through this checklist on paper works, but keeping it current across several properties at once is where most buyers lose track. A private tool can provide a place to log each offer's price, contingencies, attached documents, and deadlines against the specific property it belongs to, so nothing depends on a scattered inbox or a messy spreadsheet.
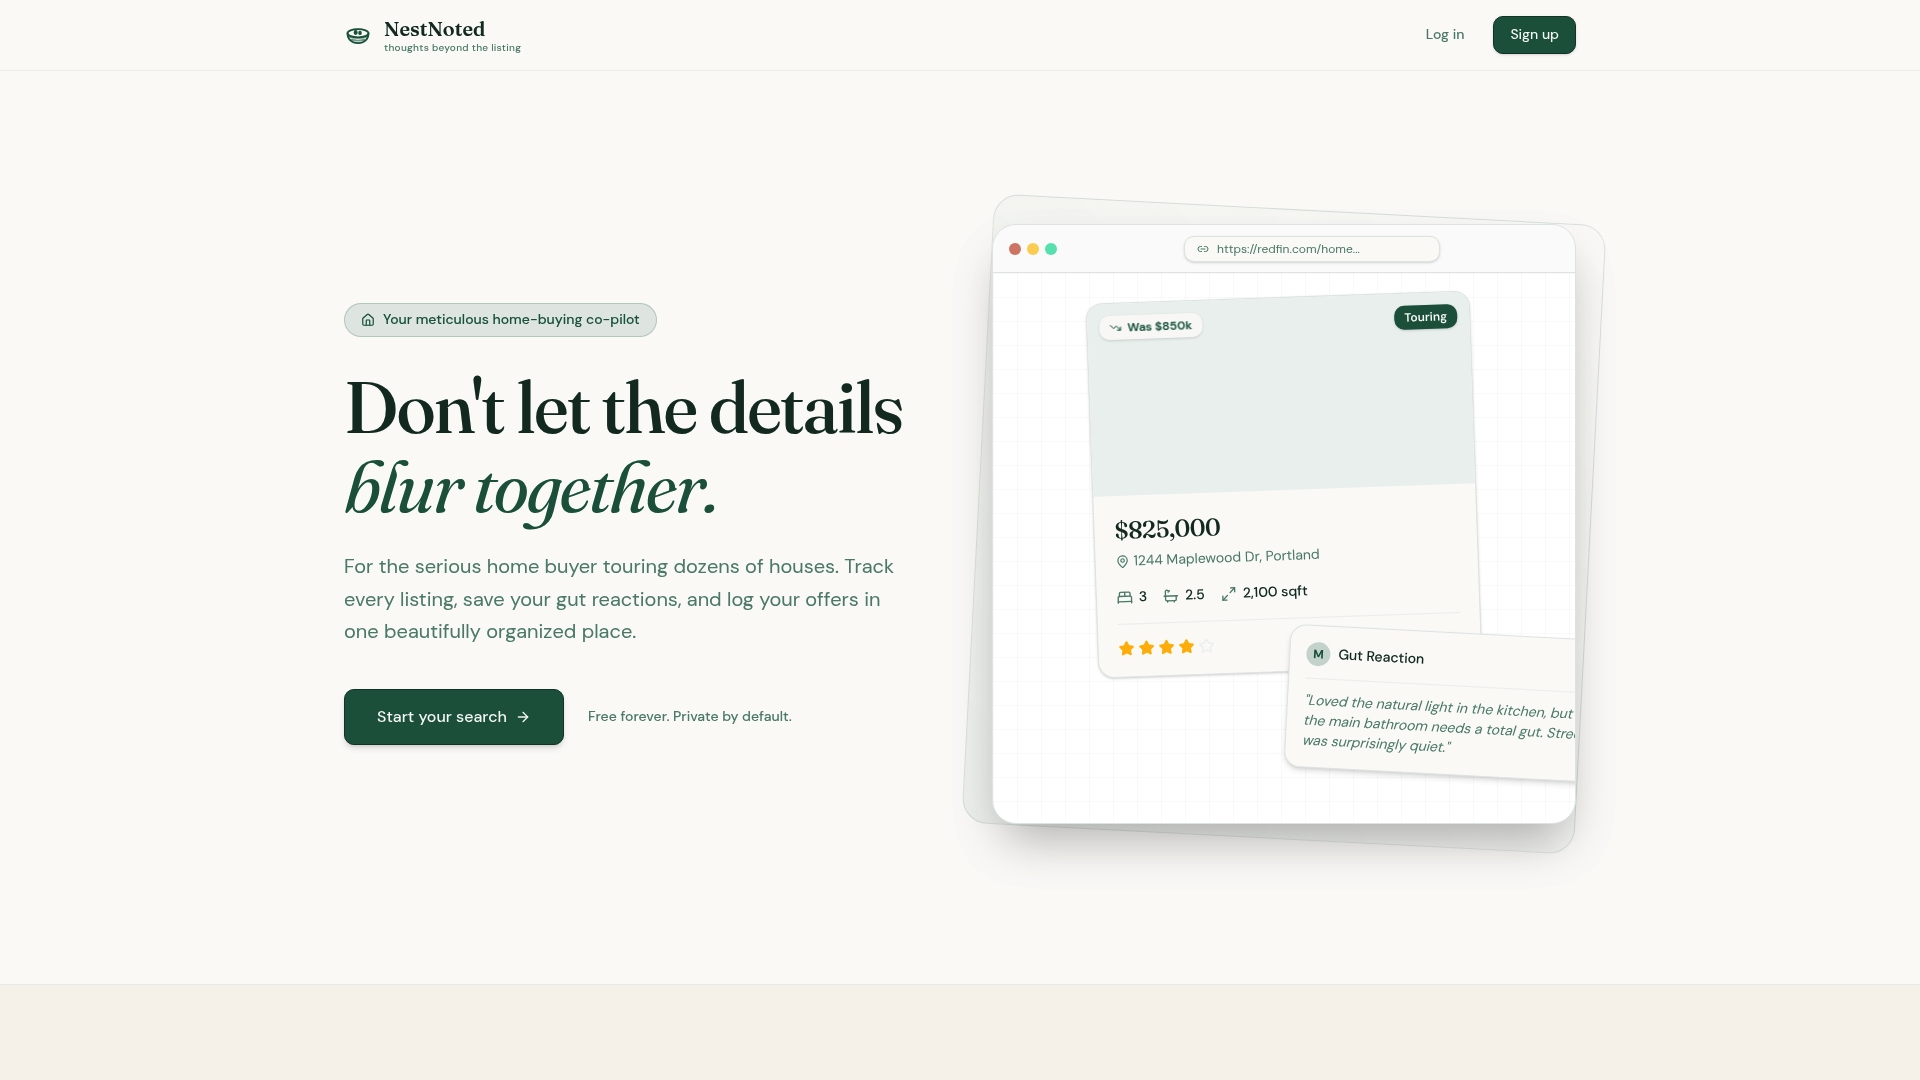
- Private notes and ratings on every property you've toured, visible only to you and anyone you choose to share with.
- Document storage tied to each listing, so pre-approval letters and disclosures stay attached to the right address.
- Side-by-side comparisons when you're weighing more than one active offer.
NestNoted is an organizational tool, not a substitute for legal or lender advice, but it keeps the checklist above in one place instead of a dozen. Visit NestNoted to see how it fits into your next offer.
FAQ
What are the terms of the offer?
The core terms are the identified property and parties, purchase price and payment structure, earnest money amount and escrow handling, contingencies with deadlines, closing and possession dates, and required disclosures and signatures. A complete offer also lists included personal property and any seller credits or repair obligations, as outlined in NAR's consumer guidance.
What are five essentials of a valid offer?
A complete offer needs an identified property and named parties, a definite price and payment plan, clear earnest money terms, contingencies with deadlines, and signed contract documents along with required disclosures. Missing any of these can leave the offer open to disputes or delay acceptance, based on NAR's consumer guide.
What are some common contract terms?
Common terms include financing, appraisal, inspection, title, home-sale, and HOA contingencies, each with its own deadline and notice requirements, according to NAR's guide to contract contingencies. Offers also typically specify possession dates, included fixtures, and closing cost allocations between buyer and seller.
What should I include with my offer besides the contract?
Attach your signed contract pages, a lender pre-approval letter or proof of funds, and any earnest-money receipt once funds are sent. For homes built before 1978, include the federally required lead-based paint disclosure and acknowledgment described in EPA guidance.
How much earnest money should I offer?
Earnest money deposits commonly range from 1% to 10% of the purchase price, depending on local custom and how competitive the market is, per NAR's reporting. State the amount as a specific dollar figure in your offer rather than a percentage, and confirm which escrow holder will receive the funds.
Sources
- Consumer guide: Escrow and earnest money (NAR)
- Lead-based paint disclosure rule (EPA / Title X guidance)
- CFPB: Know before you owe (loan disclosure guidance)