
Start by pulling recent, similar sales from an agent's MLS access, your county's deed records, and a consumer portal like Zillow or Redfin, then verify each one before you trust it. These sources cover different gaps: MLS gives you transaction detail, county records confirm the real sale price, and portals show you the broader market fast. Adjust for condition and timing, and remember that a professional appraisal can still reshape your negotiating options later.
TL;DR:
- Fannie Mae’s formal appraisal guidance typically calls for at least three closed comparables; prioritize similar homes in the same neighborhood before expanding your search.
- Check contract and closing dates separately because they can be weeks apart, and assess condition, lot size, and layout before comparing sale prices.
- Do not rely on simple averages or price per square foot alone; renovation status, repairs, and lot features can shift a home’s value.
- If an appraisal falls below the contract price, buyers may renegotiate, cover the gap with a larger down payment, or cancel, depending on contract terms.
- CFPB guidance recommends requesting Loan Estimates from at least three lenders; comparing offers can save $600 to $1,200 per year and improve financing negotiations.
Table of Contents
- What makes a strong comparable: attributes to match and why they matter
- Step-by-step: pull and vet three usable comps
- How to adjust comps: basic time, condition, and feature adjustments buyers should understand
- Using comps to set an offer and negotiate
- Common mistakes buyers make when relying on comps
- Why organized tracking improves comp decisions
- A buyer's perspective on using comps responsibly
- Track your comps and offers without losing the details
- FAQ
- Sources
- Primary authoritative links referenced in this guide
What makes a strong comparable: attributes to match and why they matter
Not every recent sale nearby counts as a usable comp. The strength of a comparable comes down to a handful of attributes, and getting these wrong is how buyers end up anchored to the wrong number.
Recency matters first. An older sale in a fast-moving market may already be stale, so lean on the most recent closings you can find, and note whether you're looking at contract date or final sale date since the two can be weeks apart.
Location comes next. A nearby home in the same subdivision is a far better comp than one in a competing neighborhood with different schools or HOA fees. Expand your radius only when same-neighborhood sales are too thin to work with.
Size and layout need to be close enough that an adjustment makes sense rather than a guess. A smaller ranch isn't a fair comparison for a much larger two-story, even if both sold recently on the same block.
Condition at sale is often the single most overlooked variable. A sale that was actually a teardown, or one that followed a gut renovation, can distort price-per-square-foot figures badly if you don't know which one you're looking at.
Other factors worth checking:
- Lot size, view, and flood zone status can shift value independent of the structure itself.
- HOA fees and restrictions affect what buyers are willing to pay.
- Whether the buyer was an investor or owner-occupant can signal atypical financing or urgency.
- Seller concessions or below-market financing can make a sale price look lower or higher than the true market value.
Fannie Mae guidance states that a comparable property does not need to be identical but should be competitive and appealing to the same market participants, with appraisers selecting the best indicators of value and applying market-supported adjustments for the differences that remain.
Step-by-step: pull and vet three usable comps
Follow these steps in order, and resist the urge to skip verification just because a number looks reasonable.
- Document the subject property first: finished square footage, lot size, bed and bath count, condition, garage, and any recent improvements. You can't judge a comp without a clear baseline.
- Set your search parameters: use recent sales where possible, limit your search to the same neighborhood before expanding, and look for properties with similar square footage.
- Pull candidate sales from at least two sources, recording sale price, sale date, days on market, financing type, and any known concessions for each one.
- Verify the sale details through county deed records or by asking your agent to confirm numbers pulled from a portal, and flag any listing where condition information is missing or unclear.
- Rank your candidates by similarity to the subject property and narrow to the strongest matches for your actual analysis.
For organizing this process without losing track of details across multiple tours, our open house tracker guide covers how to record impressions consistently while you're still on-site.
Pro Tip: Keep a single running note per comp with the five numbers that matter most (price, date, size, condition, concessions) so you can compare them side by side instead of flipping between tabs.
How to adjust comps: basic time, condition, and feature adjustments buyers should understand
Averaging three sale prices and calling it a day is tempting, but it's not how professionals do it, and it can leave you badly off target.
Fannie Mae guidance states that appraisers select the best indicators of value and apply market-supported adjustments for differences rather than relying on simple averages. Appraisers also document the reasoning and magnitude behind each adjustment. Fannie Mae's adjustments guidance notes that time adjustments should be supported by evidence such as home price indices or statistical analysis, not a flat percentage pulled from memory.
Common adjustment categories include:
- Market time trend, since prices often drift between the comp's sale date and today.
- Condition or renovation status, which can swing value substantially even on identical floor plans.
- Bedroom and bathroom count differences.
- Garage presence and lot size.
You don't need appraiser-level precision, but you can reflect direction and rough magnitude in your notes. If a comp sold for a lower price but needed a new roof the subject property already has, note that the comp should probably be adjusted upward before comparing it directly.
A comparable sale does not need to be identical to the subject property, but it does need to be competitive and appealing to the same market participants.
This is also why price per square foot is a blunt tool on its own: two homes at the same price per square foot can represent very different conditions, and treating them as equivalent skips the exact adjustment step appraisers are trained to make.
Using comps to set an offer and negotiate
Once you've weighted your strongest comps, you should have a defensible range rather than a single number, and that range is what drives your offer strategy.
- Convert your comp range into an offer price, leaning toward the higher end in a competitive market and the lower end when inventory is sitting longer than average.
- Choose your approach: an aggressive offer near or above the top of your range when you expect competition, a market-rate offer near the middle when conditions are balanced, or a contingent offer when you want appraisal and inspection protections built in.
- Understand what an appraisal contingency does for you: if the home appraises below the contract price, CFPB guidance notes that buyers can often use the low appraisal to negotiate a lower price or, depending on the contract terms, cancel the purchase.
- Get multiple Loan Estimates before you negotiate financing. CFPB guidance recommends requesting offers from at least three lenders, which can save $600 to $1,200 per year and gives you a concrete bargaining chip with your preferred lender.
When you present your findings to a seller or agent, lead with the verified numbers, not your gut feeling: "recent closed sales, adjusted for condition, support a range of X to Y" lands far better than a vague sense that the price feels high.
Common mistakes buyers make when relying on comps
A few errors show up again and again, and all of them are avoidable with a bit more discipline.
- Trusting consumer portal prices without verifying them against county records or MLS data.
- Using distant or dissimilar sales just because they're the only recent ones available, without documenting why an adjustment is needed.
- Comparing price per square foot across homes in very different condition, which hides the real variable driving the price.
- Keeping notes scattered across texts, screenshots, and memory, which leads to inconsistent judgment calls across different homes you tour.
Why organized tracking improves comp decisions
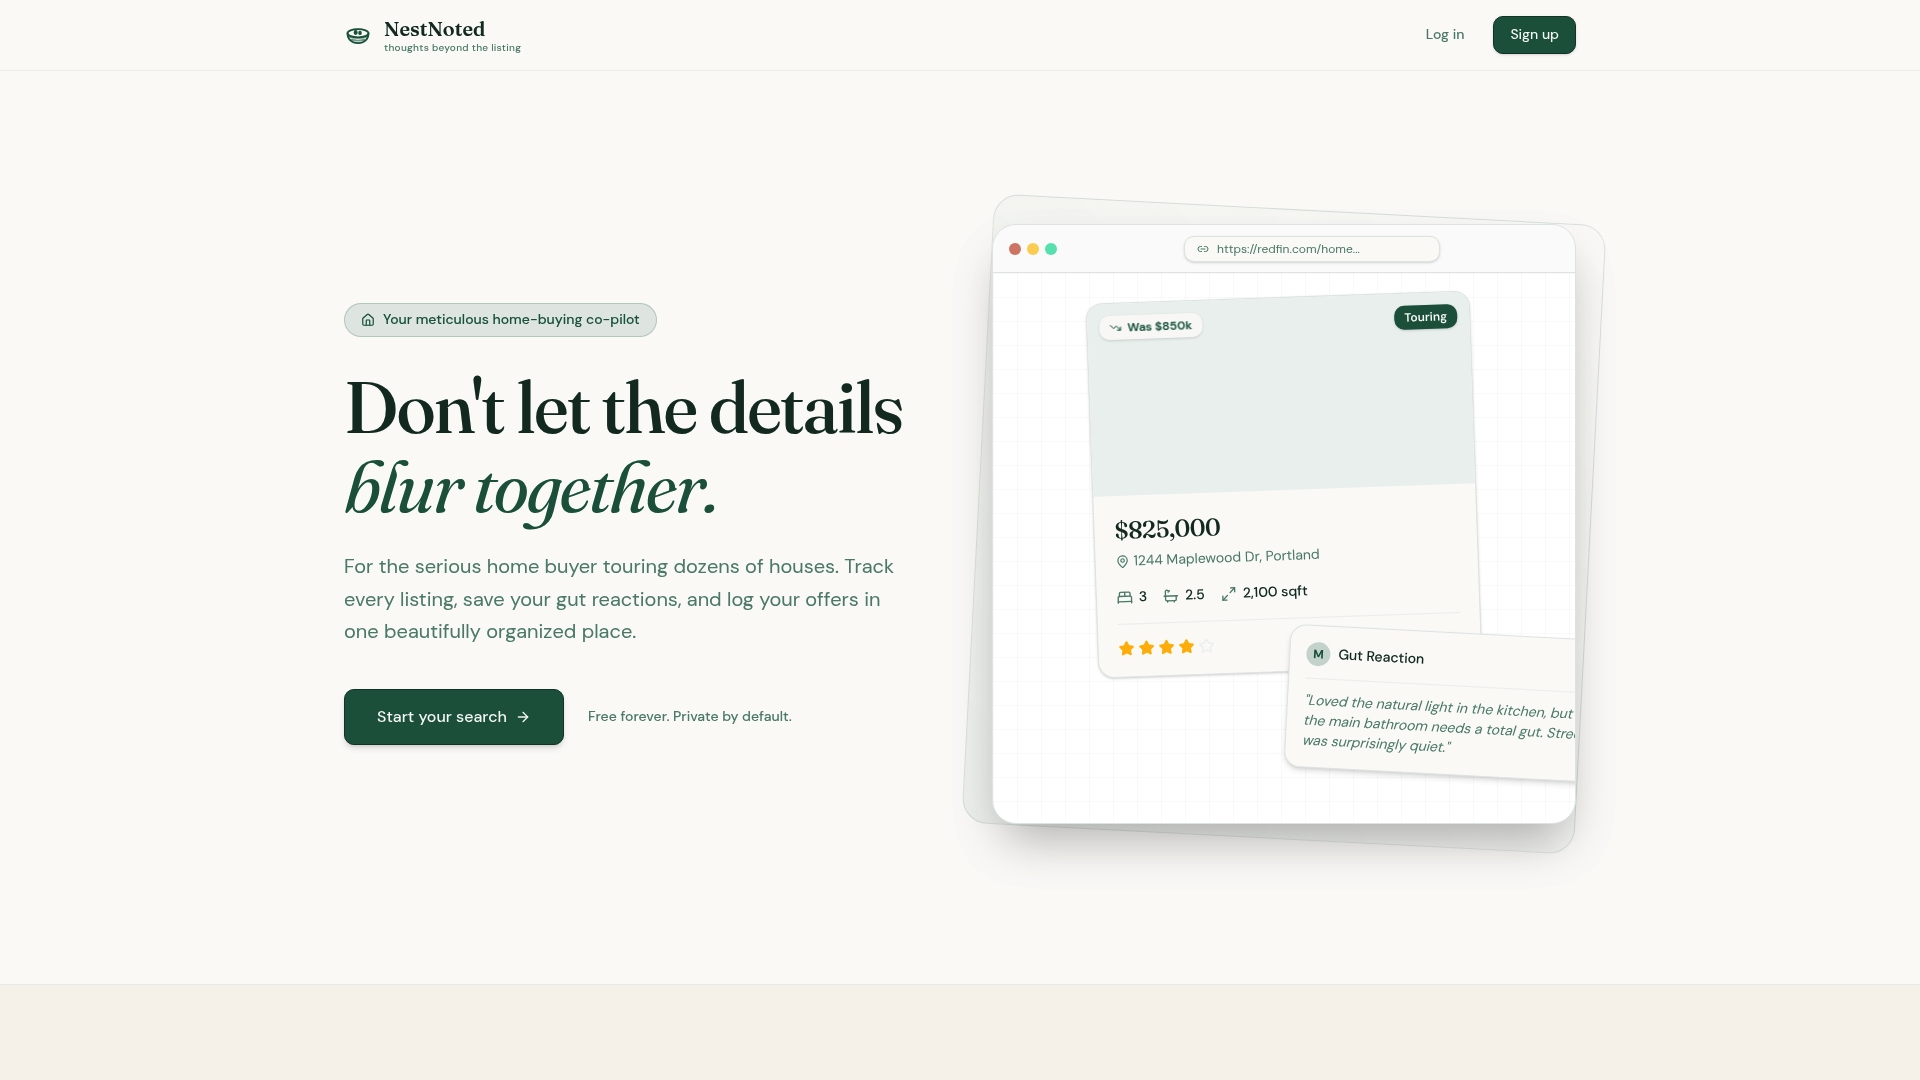
Buyers who tour several homes in a short window tend to blur details together, which makes condition-adjusted comparisons harder to apply consistently from one house to the next. Tracking price drops, past offers, and your own impressions in one place builds real negotiating leverage instead of relying on memory. A privacy-first tool like NestNoted supports private notes, side-by-side comparisons, price alerts, and collaboration between buyers and agents, which matches exactly this kind of structured comp work.

A buyer's perspective on using comps responsibly
Comps are evidence, not proof. I'd rather see a buyer walk into a negotiation with three verified, condition-adjusted sales than one unverified number pulled from a portal. Pair that work with multiple Loan Estimates and real appraisal protections, and you're negotiating from a position that can actually hold up.
— Antony
Track your comps and offers without losing the details
Juggling comps, tour notes, and offer history across spreadsheets and text threads is how good details get lost between showings. We built NestNoted around keeping every note private by default, so you and your agent can compare homes honestly without worrying who else sees your impressions.
- Private notes and ratings tied to each property you tour.
- Side-by-side comparisons that make condition and price differences easy to see.
- Price-drop alerts so you know when a comp's range shifts.
- Shared workspaces for collaborating with an agent or a partner on the same search.
If you're touring multiple homes and trying to keep your comp research straight, create a free NestNoted account and start tracking the details before they blur together. For a closer look at side-by-side comparisons specifically, our home comparison chart guide shows the format in action, and our scorecard for tracking offers is a natural next step once you're ready to make one.
FAQ
How many comps do I need to find comps as a buyer confidently?
Strong, verified comparable sales can support an offer when they're recent and genuinely similar to the subject property. Fannie Mae's appraisal guidance typically requires at least three closed comparables in a formal sales comparison report, which is a reasonable benchmark for buyers to follow too.
What happens if the appraisal comes in below my offer price?
You generally have options rather than an automatic deal collapse. CFPB guidance explains that buyers can often use a low appraisal to negotiate a reduced sale price, increase their down payment to cover the gap, or in some cases cancel the contract depending on its terms.
Should I trust price per square foot when comparing homes?
Price per square foot is a useful starting filter but a weak final measure, because it hides differences in condition, renovation status, and lot features. Two homes at the same rate per square foot can represent very different levels of finish, so adjust for condition before relying on the number.
Why should I get multiple Loan Estimates while I'm working on comps?
Comparing Loan Estimates from different lenders gives you real leverage on financing terms at the same time you're building leverage on price. CFPB guidance recommends requesting offers from at least three lenders, which can save $600 to $1,200 per year and strengthens your negotiating position overall.
Is it worth inspecting plumbing or other systems before trusting a comp's condition?
Yes, since a comp's listed condition can hide costly issues that affect true value, and the same applies to the home you're bidding on. A pre-closing plumbing inspection can catch problems that would otherwise only surface after you've already set your offer based on comps.
Sources
Every source has a blind spot. Knowing which one to trust for which fact keeps you from building an offer on bad information.
An agent with MLS access can pull a comps packet showing sale price, days on market, concessions, and financing type, details that rarely make it onto a public-facing site. Ask directly for "a comps packet for [address] with recent closed sales." This is the most complete source for transaction detail, but it does require a working relationship with an agent.
County property and deed records are the authoritative record of what a home actually sold for. You can usually search these online through your county assessor or recorder's office by address or parcel number. They are slower to update and rarely include condition notes, but the price itself is hard to dispute once filed.
Consumer portals such as Zillow, Redfin, and Realtor.com are fast and free, and good for scanning a neighborhood quickly. Their weakness is what they leave out: seller concessions, whether the sale involved a cash buyer, or whether the home needed a full renovation. Houses can show the same price per square foot while one needed extensive repairs and the other didn't.
Open houses, active listings, and pending sales add useful context even though they are not closed comps. They show you what sellers believe the market will bear right now, which is a different question from what buyers actually paid.
A practical rule for sorting these:
- My appraisal is less than the sale price. What does that mean for me? | Consumer Financial Protection Bureau
- Request and review multiple Loan Estimates | Consumer Financial Protection Bureau
- Comparable Sales | Fannie Mae
- Adjustments to Comparable Sales | Fannie Mae
For a deeper look at when each platform earns your trust, our comparison of MLS and Zillow data walks through specific scenarios where the two disagree.
Primary authoritative links referenced in this guide
These sources back the appraisal, lending, and comp-selection claims covered above, drawn from federal consumer protection guidance and Fannie Mae's appraisal standards.
- My appraisal is less than the sale price. What does that mean for me? | Consumer Financial Protection Bureau
- Request and review multiple Loan Estimates | Consumer Financial Protection Bureau
- Comparable Sales | Fannie Mae
- Adjustments to Comparable Sales | Fannie Mae
- Sales Comparison Approach Section of the Appraisal Report | Fannie Mae
- Upgrade Your Home's Value | One Day Doors & Closets
- Avoid Costly Sewer Repairs: Inspect Plumbing Before Closing for Buyers & Sellers