
When you walk into a listing with an HOA, write down three things on the spot: the fee amount, how often it's billed, and exactly what it covers. Then convert that figure to a monthly cost and add it to your mortgage, taxes, and insurance estimate. Keep these notes private so you and your agent can compare properties honestly, without the fee numbers getting lost between showings.
TL;DR:
- Record each listing’s fee, billing schedule, inclusions, special assessments, and management contact during the tour, then verify the figures with the association.
- Listing figures may be outdated; request governing documents, the current budget, a reserve study, and recent meeting minutes, then ask management about pending assessments.
- Divide quarterly dues by three and annual dues by twelve, then add the monthly amount to principal, interest, taxes, and insurance for total housing cost.
- Frequent assessments, weak reserves, or high owner delinquencies can signal future costs; ask about budget shortfalls, litigation, and the latest reserve study date.
Table of Contents
- Checklist: exact HOA fee fields to capture for each listing
- Where to find and verify HOA fee information
- How to compare HOA fees and fold them into monthly affordability
- Red flags and the exact questions to ask the HOA, seller, or agent
- Private tracking workflow and field set for touring buyers
- Why a disciplined, private approach to HOA tracking matters
- How NestNoted maps to the checklist for private HOA fee tracking
- FAQ
- Sources
Checklist: exact HOA fee fields to capture for each listing
Touring five or six homes in a weekend turns into a blur fast, and HOA fees are the detail buyers forget first because they rarely show up clearly on a flyer. Capture these fields the moment you see the listing or walk the property, before the next showing erases the specifics.
- Amount and billing frequency: monthly, quarterly, or annual, since this changes the true monthly cost significantly.
- What's covered: water, trash, insurance, landscaping, amenities, parking, or exterior maintenance.
- Special assessments and transfer fees: any one-time charges tied to the sale or recent capital projects.
- Billing contact and management company: who sends the invoice and who you'd call with questions.
- Reserve fund notes and delinquency signs: anything the agent or listing mentions about financial health.
- A quick private rating: your gut read on whether the fee feels justified, plus any negotiation angle.
The first four are non-negotiable. Skip them and you're comparing listings on guesswork instead of numbers.
Where to find and verify HOA fee information
The listing itself is only a starting point. HOA fees quoted on a flyer or portal often reflect last year's figure, and the real number can change before closing.
- Check the MLS HOA fields and agent disclosure first. These give you a baseline amount and frequency, though they're not always current.
- Request the full HOA packet. Ask for the CC&Rs, bylaws, current budget, reserve study, and recent meeting minutes. The National Association of Realtors recommends reviewing governing documents, financial statements, and assessment schedules before you commit, since these documents reveal fee history and reserve strength that a listing sheet never will.
- Call the management company directly. Ask about the billing cycle, the due date, and whether any assessment is pending but not yet reflected in the public fee.
- Know your state's disclosure timeline. Some states require sellers to hand over HOA documents before closing, which gives you a formal window to verify everything you recorded during the tour.
Agents should treat the HOA fee as a material fact worth documenting early, the same way they'd note square footage or lot size, because a fee that looks small on paper can shift the whole affordability picture once assessments or inclusions are factored in.
How to compare HOA fees and fold them into monthly affordability
Comparing HOA fees across listings only works once every number is speaking the same language. A $450 monthly fee and a $1,350 quarterly fee are identical costs, but they look wildly different on paper until you normalize them.
- Convert everything to monthly. Divide quarterly fees by three and annual fees by twelve.
- Add the normalized fee to your full housing cost. The CFPB's monthly payment worksheet recommends stacking condo or HOA dues on top of principal, interest, property taxes, and homeowner's insurance to see the real monthly burden, not just the mortgage payment.
- Adjust for what's included. If one HOA covers water and another doesn't, subtract an estimated utility cost from the second listing's comparator so you're comparing like with like.
- Treat special assessments as near-term fee increases. Re-score a listing lower if a known assessment is coming, even if the regular dues look reasonable.
HOA fees nationally range from a few hundred dollars a month to more than $1,000, according to the Consumer Financial Protection Bureau, which means a fee at the high end can rival a car payment and deserves the same scrutiny as your mortgage rate.
Say a listing carries a $500 monthly HOA fee and a mortgage payment (principal and interest) of $2,100, plus $300 in taxes and $150 in insurance. Your total monthly housing cost is $3,050, not the $2,550 a buyer who ignores the HOA fee might assume.

Red flags and the exact questions to ask the HOA, seller, or agent
A low HOA fee isn't automatically good news. If the reserve fund is thin, that low number is often a sign the association is deferring costs rather than avoiding them.
- Frequent special assessments suggest the regular dues aren't covering real expenses.
- Low reserve fund balances relative to the property's age or size point to upcoming capital shortfalls.
- High delinquency rates among owners can force remaining residents to absorb the gap through higher fees.
Ask directly: when was the last special assessment, and what was it for? What does the most recent reserve study show, and when was it conducted? Is there a current budget shortfall? What percentage of owners are delinquent on dues? Is there any pending litigation involving the association? Request copies of recent meeting minutes and a certificate of insurance while you're at it, since both documents often reveal issues an agent wouldn't otherwise mention.
If the answers raise concerns, that's leverage. Push for a price adjustment, add an inspection contingency specific to HOA financials, or flag the figures for your lender before you go further.
Pro Tip: Ask for the reserve study date before you ask for the reserve amount. A study that's five years old tells you the "healthy" number on paper may already be outdated.
Private tracking workflow and field set for touring buyers
A consistent workflow matters more than any single tool, but the tool decides whether you stick with it.
- Capture on-site or immediately after the tour. Record the fee amount, frequency, what's included, special assessments, billing contact, a link to HOA documents, reserve notes, your private rating, a timestamp, and the MLS number.
- Tag each entry by search round. Grouping by week or neighborhood makes later comparison faster than scrolling through a single long list.
- Normalize every fee to monthly as you enter it, rather than waiting until comparison day.
- Score and rank listings once you have three or more comparable entries, using total monthly housing cost rather than fee amount alone.
Keeping this process private matters as much as keeping it organized. Honest notes, including the unflattering ones, only happen when you're not worried about a seller's agent or a public review seeing them. A private tracker that imports listings automatically and lets you compare properties side by side removes the friction that usually kills a tracking habit by the third showing. For related on-site habits, see our guide to capturing tour impressions with an open house tracker and our notes on tracking MLS numbers privately so every HOA entry stays tied to the right listing.
Why a disciplined, private approach to HOA tracking matters

Scattered notes, a screenshot here, a text to your agent there, create regret weeks into a search, when you can't remember which listing had the $600 fee and which had the special assessment. Writing it down consistently removes that fog.
Privacy is what makes the comparison honest. Buyers rate properties more candidly when they know the notes aren't visible to a seller's agent or posted publicly, and that honesty is what actually improves alignment between a buyer and their agent, not a longer conversation. A disciplined process also means fewer surprises at inspection or closing, because the reserve concerns and assessment history were flagged weeks earlier, not discovered in a document dump three days before you sign.
— Antony
How NestNoted maps to the checklist for private HOA fee tracking
Comparing HOA fees across a dozen showings by memory or spreadsheet is where most buyers lose the thread, and that's a common gap personal property management tools aim to close. These tools give you a private workspace where every HOA fee, inclusion, and assessment note lives next to the listing it belongs to, often imported automatically instead of retyped.
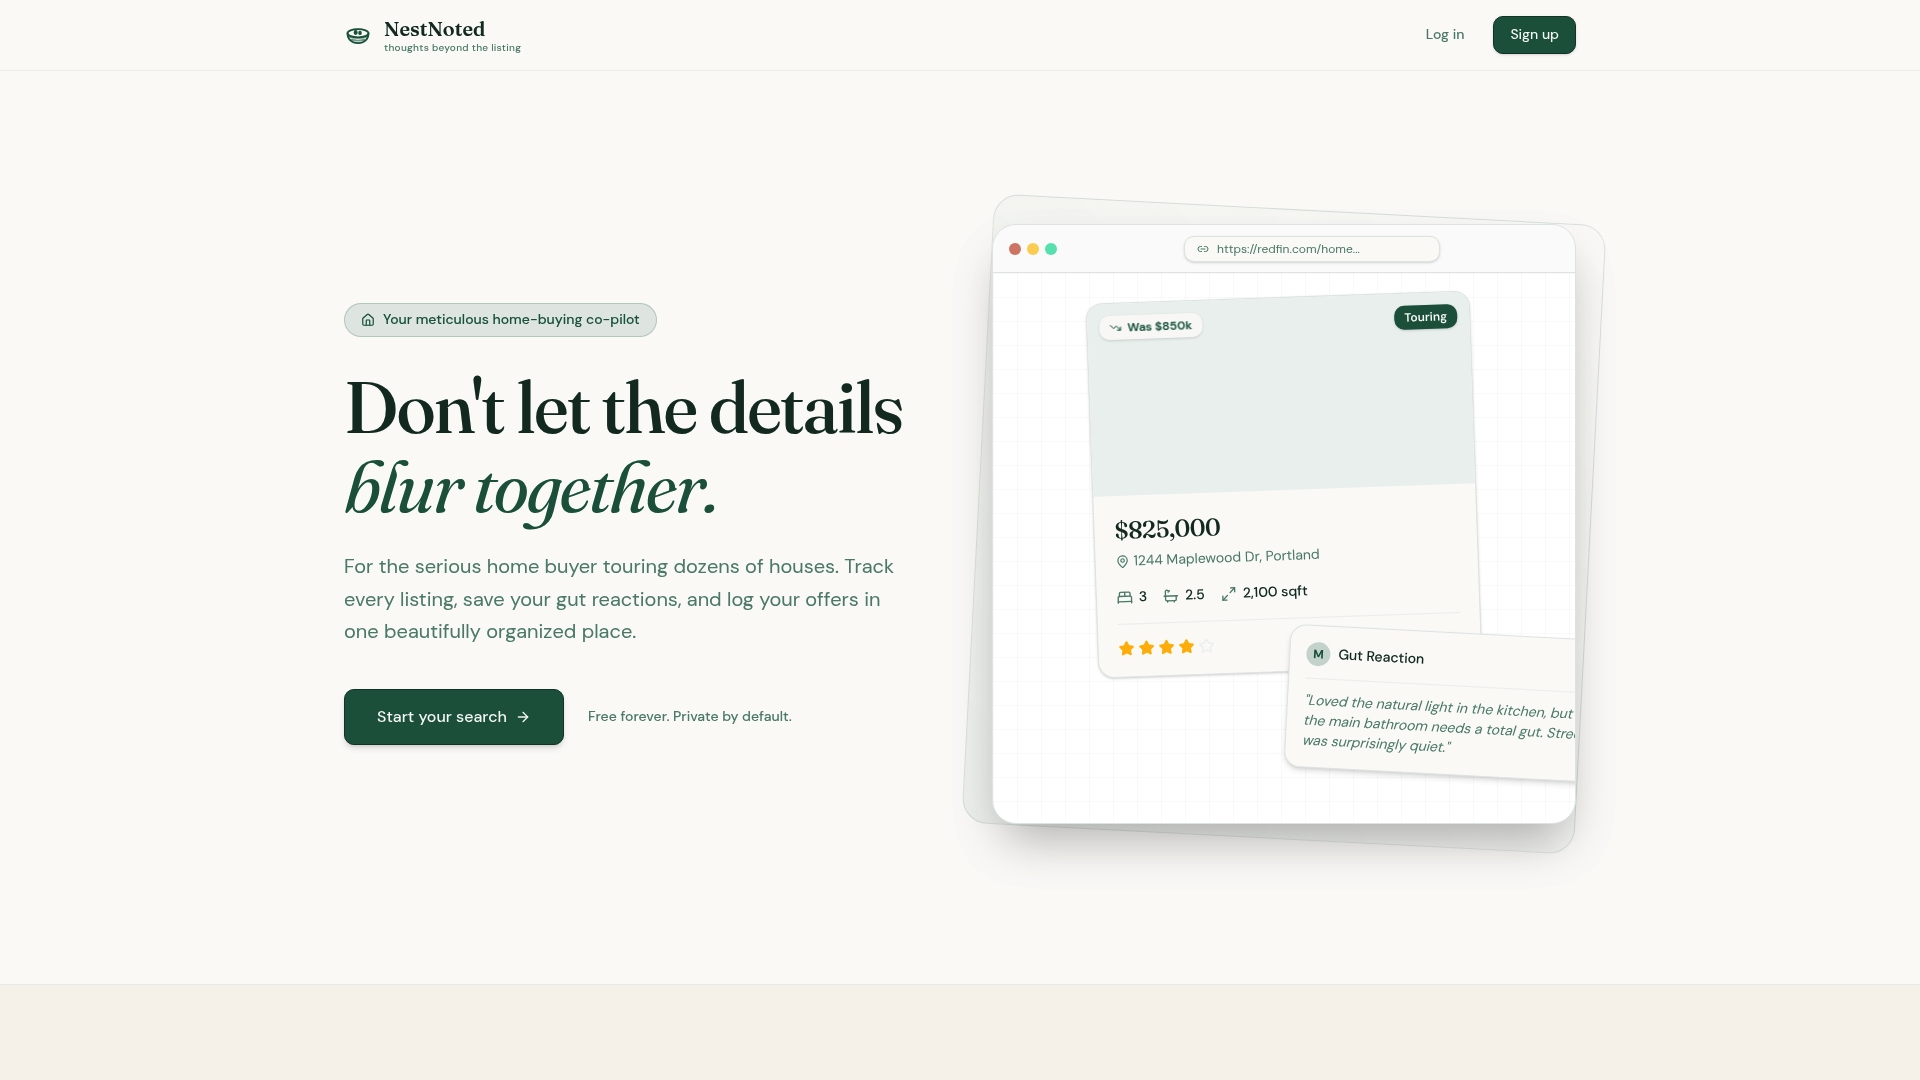
- Automatic listing import can pull property details to avoid re-entering fee data by hand.
- Private notes by default help keep your HOA red flags and ratings confidential.
- Side-by-side comparison allows normalized monthly costs to be viewed across multiple properties.
- Offer and pipeline tracking supports moving forward once you've narrowed down finalists.
| Workflow need | NestNoted feature |
|---|---|
| Capture fee fields fast | Listing import |
| Compare normalized costs | Side-by-side comparison |
| Keep notes confidential | Private notes by default |
| Move forward on a choice | Offer and pipeline tracking |
Start a free NestNoted account and import your current listings to see your HOA notes organized in one place.
FAQ
How do I record an HOA fee I see during a tour?
Write down the amount, the billing frequency, and exactly what it covers the moment you see it, since these details are easy to mix up between showings. Confirm the figure later against the HOA packet or management company, since listing sheets aren't always current.
How do I compare HOA fees across different listings?
Convert every fee to a monthly amount, then add it to your mortgage payment, taxes, and insurance to get a true total housing cost. Adjust for what each fee includes, since a higher fee that covers water and insurance may actually cost less than a lower fee that covers nothing.
What's a normal range for HOA fees in the U.S.?
HOA and condo fees typically run from a few hundred dollars a month to more than $1,000, according to the CFPB. The National Association of Realtors reports a typical monthly HOA fee, which gives you a useful benchmark for spotting an unusually high or low quote.
What HOA documents should I ask for before making an offer?
Request the CC&Rs, bylaws, current budget, reserve study, and recent meeting minutes, all of which reveal fee history and financial health. Fannie Mae's guidance on buying a condo notes that reserve studies and minutes give early warning of upcoming assessments.
Does NestNoted help me track HOA fees privately?
Yes. NestNoted lets you log HOA fee amounts, inclusions, and notes per listing in a private workspace, then compare them side by side without the data being visible to anyone else unless you choose to share it.
Sources
For deeper reading on HOA fee structures and underwriting expectations, the CFPB's monthly payment worksheet, NAR's guidance on HOA disclosure, and Fannie Mae's condo documentation standards cover the financial and procedural details in more depth. For management-side context, see this partner resource on HOA package management.
- Consumer Financial Protection Bureau — Are condo/co-op fees or homeowners association dues included in my monthly mortgage payment?
- NAR — Navigating HOA rules: considerations for real estate agents, buyers and sellers
- CFPB monthly payment worksheet — buying a house